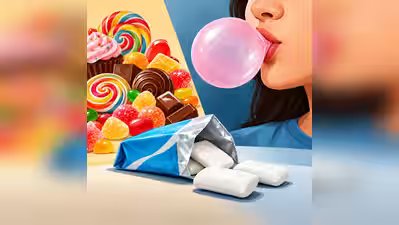
Ahmedabad: Chewing gum may be consumed for its sweet flavour, but since it is not an edible item, it cannot be classified as a sweet or sweetmeat and therefore does not qualify for the lower 4% VAT slab, Gujarat High Court has held. Ruling that chewing gum attracts VAT at 12.5%, the court allowed the state govt’s appeal against an order of the Value Added Tax tribunal.The case traces back to Feb 2007, when a commercial tax officer visited the premises of Cad Mak Chew Foods, a manufacturer of peppermint, sugar candy, sakariya and chewing gum. After scrutiny of records, the assessing officer in 2011 raised a total tax demand of Rs 9.83 lakh, holding that chewing gum sales attract VAT at 12.5% rather than 4%. A penalty was also imposed.Cad Mak Chew Foods challenged the demand. A deputy commissioner reduced the penalty but confirmed the 12.5% VAT rate on chewing gum. The company then moved the VAT tribunal and won relief there, after the tribunal treated chewing gum as sweet and sweetmeat covered by Entry 74A of the VAT Act, making it taxable at 4%. In 2014, the tribunal had said, “The product is consumed for the sweet juice and therefore even though at the end rubber is thrown out, they do not cease to be eatables”.The state govt took the fight to the high court, arguing chewing gum belongs under the residuary Entry 87 and therefore attracts the higher slab. The company backed the tribunal’s approach, maintaining that bubble gum is mainly consumed for sweet juice and should be treated as a sweet and confectionery item for taxation.Before the HC, the state stressed that chewing gum is not expressly mentioned in Entry 74A and invoked Supreme Court precedent on using a common parlance test for classification.A bench of Justice Bhargav Karia and Justice Pranav Trivedi set aside the tribunal’s view, holding it was contrary to apex court findings that chewing gum is not an eatable product. The bench said, “We are of the opinion that the Tribunal has committed an error in holding that chewing gum is taxable as ‘sweets and sweetmeats’ under Entry 74A of the Schedule II of the Gujarat Value Added Tax Act, 2003 and consequently, deleting the interest and penalty. We, therefore, answer both the questions in favour of the Revenue and against the assessee and hold that ‘chewing gum’ cannot be classified as ‘sweets and sweetmeats’ under Entry 74A of the Schedule II of the Gujarat Value Added Tax Act, 2003.”